
Saving rates: when accounting harmonisation reduces differences between countries
Bulletin No. 265, article 1. Differences in advanced economies’ saving rates are a well-known phenomenon: the United States consistently saves less than France, and France saves less than Germany. But which saving rate are we referring to? Gross or net? Accounting standards vary from country to country. For example, in 2025, the saving rate in the United States was 4.6% according to national statisticians but was 10.7% when applying the harmonised method proposed by the OECD and Eurostat. Although the harmonised method reduces differences between countries, it does not eliminate them. Saving rates are structurally linked to certain institutional characteristics, such as pension systems (by repartition – “pay-as-you-go” – or by capitalisation – “funded”), the boundary between private and public consumption (particularly education and healthcare), and the weight of tax on consumption. It is important to properly understand these structural contributions, notably to inform international discussions on imbalances between saving and investment.

1 Saving rates: what are we referring to?
Savings account for the part of households’ gross disposable income (GDI) that is not spent or “consumed”. Where “Conso” denotes household consumption, the saving rate is defined as the ratio of savings to GDI:
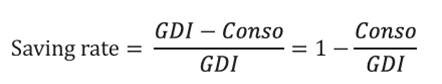
Household savings are invested in fixed capital (housing, and professional equipment in the case of sole proprietorships) and financial assets. The concept of the saving rate is sometimes reduced to the financial saving rate.
Differences in accounting standards internationally make comparing saving rates between countries more complex (see Table 1 and box). For example, Germany and the United States calculate a net saving rate by deducting the consumption of fixed capital – which corresponds to the reduction in the value of fixed assets used – from gross savings. The definition of GDI also varies from country to country, as does the scope of the “households” category.
Consequently, the Organisation for Economic Co-operation and Development (OECD) and Eurostat proposed a harmonised method to facilitate cross-country comparisons (Blades and Lequiller, 2014):
- the scope adopted includes sole proprietorships and non-profit institutions serving households (NPISHs) such as associations, foundations and trade unions;
- savings include compulsory contributions accumulated in employer-sponsored pension plans, but which are not directly visible in monetary flows;
- the harmonised saving rate is a gross saving rate: consumption of fixed capital is not deducted from savings or GDI.
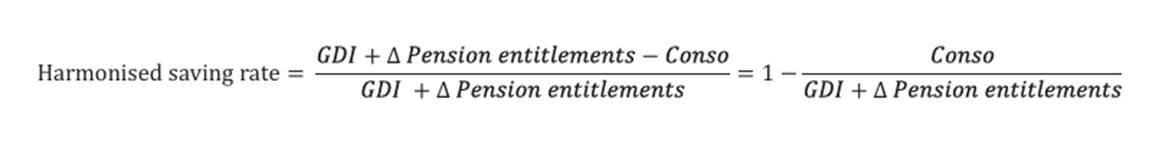
The harmonised saving rate can sometimes differ very sharply from the rate calculated nationally: in 2025, the difference in the case of Germany was more than 8 percentage points, while in the case of the United States the harmonised saving rate was more than double the published national saving rate (see Table 1). However, harmonising the calculation method does not necessarily reduce the differences between countries. In 2025, the German saving rate exceeded the rate in the United States by 8.5 percentage points when applying the harmonised method, compared with 5.7 percentage points based on the national calculations. Over the long term, Germany is conspicuous for its high harmonised saving rate compared with other advanced economies, but the United States is not alone at the bottom of the table: the harmonised saving rates of Italy, and above all Spain, are lower than that of the United States (see Chart 1).
2 Financial saving and changes in financial wealth
Financial saving, or net lending capacity, consists of savings less investment in fixed capital – both tangible and intangible assets – and capital transfers (non-financial transactions relating to the acquisition or disposal of an asset: capital taxes, investment subsidies, debt write-offs, and so on).
Financial saving is calculated as a balance, derived either from real accounts (NatAc) or from financial accounts (NatFiAc). The two measures are conceptually equivalent, but are not calculated on the basis of the same data sources. Differences depending on sources are particularly significant in the United States (see Table 2).
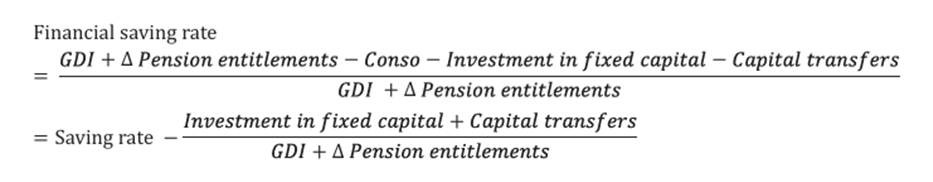
Financial saving includes new household pension entitlements, which accrue annually under funded pension schemes (see Appendix). All other things being equal, this leads to countries with this type of system having a higher saving rate than countries with pension systems based primarily on pay-as-you-go arrangements.
Changes in the financial wealth of households derive from financial saving, but also from the impact of fluctuations in the prices of assets (particularly shares and digital assets) on accumulated financial saving. However, distinguishing between these two components is not always possible. …
Download the full publication
Updated on the 14th of September 2026